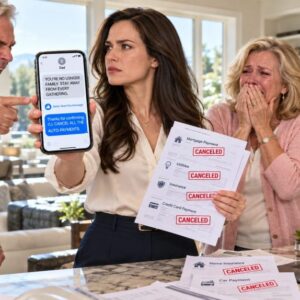
My mother slammed the front door so hard that the Thanksgiving wreath fell onto the porch.
“Don’t come back for Thanksgiving, Emily!
Your brother doesn’t need your negativity ruining another family holiday!”
I stood outside her house in Columbus, Ohio, holding a grocery bag filled with ingredients for her favorite pumpkin pie.
It was November 23, three days before Thanksgiving.
I was thirty-six years old, and somehow, my mother could still make me feel like an unwanted teenager.
“Mom, I only asked why Jason needed another twenty thousand dollars.”
She opened the door just enough to glare at me.
“Because he’s building something important!
Unlike you, he has responsibilities!”
Then she slammed it again.
I stared at the closed door.
What she didn’t know was that I’d been quietly paying her mortgage, utilities, property taxes, and medical bills for almost six years.
And her precious son Jason?
He was about to destroy my financial future.
I just didn’t know it yet.
My name is Emily Carter.
I’m a senior financial analyst at an insurance company.
I earn a comfortable salary, own a modest townhouse, and have never missed a payment in my life.
My younger brother, Jason, is thirty-three.
Five years earlier, he opened a commercial renovation company called Carter Premier Renovations.
My parents called him an entrepreneur.
I called him financially reckless.
Every failed project became somebody else’s fault.
Every unpaid invoice was supposedly temporary.
Every emergency required another family loan.
Meanwhile, my father, Richard, had retired early because of heart problems.
My mother, Linda, insisted their retirement savings were enough.
They weren’t.
When Dad’s medical expenses began piling up, I quietly arranged automatic payments from my checking account.
$1,850 monthly for their mortgage.
Another $700 for utilities, insurance, and household expenses.
And approximately $600 toward medical bills.
That was $3,150 every month.
Over six years, including several emergencies, I’d contributed more than $230,000.
I never asked for recognition.
But that afternoon, I finally asked for honesty.
Before leaving, I’d noticed an unfamiliar business envelope on Mom’s kitchen counter.
It was addressed to Carter Premier Renovations, but underneath the company name was something that made my stomach tighten.
Emily Carter — Personal Guarantor.
I asked Jason about it.
He laughed.
“It’s just paperwork, Emily.
You wouldn’t understand.”
I told him I had never guaranteed his business debts.
His smile disappeared.
Mom immediately stepped between us.
“Stop interrogating your brother!”
Then came the argument.
Then the slammed door.
Driving home, I couldn’t shake the image of that envelope.
At p.m., I logged into my credit monitoring account.
My hands went cold.
A commercial credit inquiry had appeared two months earlier.
The lender was Midwest Community Capital.
I had never applied for financing there.
Then I checked my email.
Buried in my spam folder was a message from the lender’s fraud department.
Subject: Verification Required — Carter Premier Renovations Credit Facility.
I opened it.
The message referenced a $285,000 commercial loan.
My name appeared as personal guarantor.
My home address was listed.
And the application contained a signature supposedly belonging to me.
I immediately called the lender’s emergency fraud line.
After verifying my identity, I spoke to a representative named Angela.
“Ms.
Carter, are you saying you never signed the guarantee?”
“Absolutely not.”
There was a long silence.
Then Angela said something that made my heart pound.
“Your brother submitted identification documents, income verification, and a notarized guarantee bearing your name.”
I gripped the phone.
“That’s impossible.”
“There’s something else, Ms.
Carter.
The account is already delinquent.”
“How delinquent?”
“Three payments.
And the lender has begun reviewing collection options.”
I could barely breathe.
Then Angela added:
“We also have documentation suggesting your parents were aware of the arrangement.”
I looked toward the framed family photograph hanging above my fireplace.
For six years, I’d sacrificed vacations, savings, and countless weekends to keep those people comfortable.
Now I had one terrifying question.
Had my entire family helped my brother steal my identity?
I didn’t sleep that night.
By sunrise, I had downloaded every credit report, bank statement, and payment record I could find.
The numbers were devastating.
Over seventy-two months, I’d transferred $226,800 through recurring payments.
Additional emergency expenses brought the total to $243,460.
And somehow, I was the selfish daughter.
At nine, I called my attorney, Rebecca Lawson.
She had helped me purchase my townhouse four years earlier.
When I explained the situation, her voice became serious.
“Emily, don’t confront Jason yet.
We need evidence before anyone starts destroying records.”
Rebecca instructed me to dispute the fraudulent obligation, request the lender’s complete application file, and file an identity-theft report.
By noon, I had completed the first steps.
Then Jason called.
“Emily, what did you do?”
His voice was sharp.
“What are you talking about?”
“The bank froze my remaining credit line!”
I stared at my phone.
“You used my identity to borrow $285,000.”
“Don’t be dramatic.
I was going to pay it back.”
“You forged my signature.”
“I needed collateral support!
The business was struggling!”
I felt something inside me snap.
“You could have asked.”
“You would’ve said no!”
“Exactly.”
He started shouting.
“You’re going to ruin everything!
I’ve got employees depending on me!”
I hung up.
Twenty minutes later, Mom called.
“Your brother says you’re accusing him of a crime.”
“He used my name without permission.”
“He’s family, Emily!”
“Family doesn’t forge signatures.”
“You have money.
He needs help.”
I closed my eyes.
“Mom, do you know how much I’ve paid toward your household over the last six years?”
She went quiet.
Then she whispered:
“That was your choice.”
Those five words hurt more than the slammed door.
I told her I would stop paying their expenses after the current month’s obligations were settled.
She screamed that I was abandoning them.
I replied:
“No.
I’m refusing to be financially exploited anymore.”
That evening, Rebecca emailed me the lender’s preliminary documents.
The forged signature was convincing.
The application included copies of my driver’s license and two years of tax returns.
Jason had apparently obtained them from documents I’d once stored at my parents’ house.
But the notarization bothered Rebecca.
The notary’s name was Patricia Wells.
Patricia was my mother’s longtime friend.
Rebecca checked the commission records.
Patricia’s commission was valid.
However, the notarization date was September 14.
On September 14, I had been attending a three-day corporate conference in Denver, Colorado.
My airline receipts and hotel records proved it.
Rebecca called immediately.
“Emily, we have strong evidence that you couldn’t have appeared before that notary in Ohio.”
I exhaled.
“So Jason’s finished?”
“Not necessarily.
We still need to establish who submitted the documents and who participated.”
Then Rebecca paused.
“There’s another document you need to see.”
She forwarded a scanned page.
It was titled:
Borrower Authorization and Family Financial Support Declaration.
My mother had signed it.
So had my father.
The document stated that I had voluntarily agreed to support Jason’s business financially.
I felt sick.
But the final paragraph contained something even worse.
It claimed that I had authorized the use of my townhouse as additional security.
Rebecca warned that the document did not, by itself, create a valid mortgage lien.
Still, it showed how far someone had gone to make the loan appear legitimate.
Then she pointed to a second attachment.
“Emily, look at the authorization date.”
I looked.
September 12.
Two days before the fraudulent notarization.
And beneath my parents’ signatures was a handwritten note.
“Emily must not be informed until after the Thanksgiving holiday.”
PLOT TWIST
Rebecca enlarged the original scanned page.
The handwriting wasn’t Jason’s.
It belonged to my father.
And beside his signature was a separate lender disclosure acknowledging that the business was already facing insolvency.
My father hadn’t simply known about the fraud.
He had helped plan when I would discover it.
The next morning, I drove to my parents’ house.
Not to apologize.
Not to argue.
I needed to hear my father explain why he’d betrayed me.
Dad was sitting at the kitchen table when I arrived.
Mom stood by the sink, her arms crossed.
“Emily,” Dad said quietly. “We weren’t expecting you.”
I placed the copied documents on the table.
“Then explain these.”
Mom glanced at them and immediately looked away.
Dad adjusted his glasses.
“Where did you get those?”
“From the lender.
The same lender that believes I personally guaranteed Jason’s $285,000 loan.”
His face lost its color.
“Emily, please sit down.”
“I’d rather stand.”
For several seconds, nobody spoke.
Finally, Dad sighed.
“Jason came to us in August.
His company was behind on payroll.
He said one major contract would save everything.”
“So you decided to steal my identity?”
Dad shook his head.
“We thought he could repay the money before you ever found out.”
I laughed bitterly.
“You thought that made it acceptable?”
Mom stepped forward.
“Your brother was desperate!”
“And I wasn’t?
I’ve spent six years paying bills you couldn’t afford!”
Dad stared at the documents.
Then he whispered:
“We know.”
Those two words stopped me.
“You know?”
Mom’s expression changed.
Dad looked directly at me.
“I’ve known about the mortgage payments since the beginning.”
My chest tightened.
“Then why did Mom keep telling everyone Jason was supporting you?”
Dad swallowed.
“Because she didn’t want people thinking our son was a failure.”
I turned toward my mother.
“Was protecting Jason’s reputation worth destroying mine?”
She didn’t answer.
Instead, she said:
“You’ve always been better with money.”
I stared at her.
“That doesn’t make my money yours.”
Dad covered his face.
For the first time, I noticed how exhausted he looked.
But exhaustion wasn’t an excuse.
“Did you know Jason forged my signature?”
Dad hesitated.
“Jason said he could arrange the paperwork.
He told us you would eventually understand.”
“And the handwritten note?”
Dad closed his eyes.
“I wrote it.”
“Why?”
“Because we wanted one last normal Thanksgiving before the bank started asking questions.”
I felt tears rising.
“You wanted a normal holiday while I was being set up for financial disaster?”
Mom reached for my arm.
I stepped away.
“Don’t.”
Then I asked the question that had haunted me all night.
“Did you tell Jason to use my townhouse?”
Dad shook his head.
“No.
I signed the declaration, but I didn’t understand what he was planning to attach to it.”
Whether that was completely true, I couldn’t know.
But one thing was clear.
My parents had chosen secrecy over my safety.
I left without hugging either of them.
That afternoon, Rebecca and I met with the lender’s fraud investigator.
We provided my travel records, signature samples, financial documents, and the messages Jason had sent after the credit line was frozen.
The investigator explained that the lender would review the disputed guarantee separately from Jason’s business obligation.
Rebecca also ordered a title search.
Fortunately, no mortgage or deed of trust securing Jason’s debt had been recorded against my townhouse.
The application had included a proposed property-security arrangement, but it had never been completed.
For the first time in two days, I could breathe.
The danger wasn’t over, but my home hadn’t been legally pledged.
Three days later, the lender confirmed that my personal guarantee was being treated as disputed pending its investigation.
I also froze my credit files and changed every account password.
Then came Thanksgiving.
Instead of going to my parents’ house, I hosted dinner for four friends.
We ate roasted turkey, mashed potatoes, green beans, and the pumpkin pie I’d originally planned to make for Mom.
Halfway through dinner, my phone rang.
Jason.
I ignored it.
He called again.
Then came a text.
“You destroyed my company.
I hope you’re happy.”
I showed Rebecca the message the following morning.
She told me to preserve it.
The next week, Jason’s company suspended operations.
Several customers had already complained about unfinished renovation projects, and the lender began pursuing repayment from the business.
Jason blamed me publicly.
He posted on Facebook that his wealthy sister had abandoned the family during its greatest crisis.
For years, I would have rushed to defend myself.
This time, I didn’t.
I simply stopped participating in the lie.
When relatives called asking why I was being cruel, I told them that Jason had used my identity without authorization and that the matter was under investigation.
I didn’t share private financial records online.
I didn’t threaten anyone.
I let the evidence speak through the proper channels.
In December, the lender completed its internal review and notified me in writing that it would not enforce the disputed personal guarantee against me.
Its investigation also identified serious irregularities in the notarization and identification procedures.
The matter was referred to law enforcement.
Patricia Wells, the notary, admitted during the investigation that she hadn’t witnessed me sign anything.
She said my mother had assured her that I had already agreed.
That confession hurt almost as much as Dad’s handwritten note.
Mom had recruited her friend to make the forged documents appear legitimate.
By January, Jason was facing criminal charges related to the fraudulent loan application.
Patricia was also under investigation for her role.
My parents retained an attorney because of the declaration they had signed.
I couldn’t control how the legal process would end.
But I could finally control my own life.
I canceled the automatic transfers after making sure my parents had written notice and enough time to arrange their next payments.
Dad called me in February.
“Emily, we’re selling the house.”
I sat silently.
“We can’t afford it without your help,” he continued.
“I know.”
“Your mother is having a difficult time accepting that.”
I looked around my small townhouse.
For years, I’d delayed replacing furniture, postponed vacations, and worked extra hours because I believed my parents needed me.
They had needed my money.
But they hadn’t respected the person providing it.
Dad cleared his throat.
“I owe you an apology.”
I waited.
“I knew what Jason was doing was wrong.
I told myself I was protecting the family.
But I was protecting him at your expense.”
Tears filled my eyes.
“Why wasn’t I worth protecting?”
Dad began crying.
“I don’t have an answer that makes it right.”
For once, he didn’t make excuses.
We spoke for almost an hour.
I told him I loved him, but I wouldn’t finance their household anymore.
He accepted that.
Mom didn’t.
She sent one final message.
“A good daughter would never let her parents lose their home.”
I stared at it for several minutes.
Then I replied:
“A good parent would never sacrifice one child’s future to protect another child’s mistakes.”
She didn’t respond.
In March, my parents moved into a smaller condominium they could afford with their retirement income.
Jason’s company entered bankruptcy proceedings.
The criminal case remained pending, and I had no intention of interfering with it.
My parents’ attorney advised them to cooperate with investigators.
I hoped they would.
But their choices were no longer mine to repair.
By summer, I’d saved more money than I had in years.
I took a vacation to Maine with my best friend, Sarah.
We spent mornings walking along the coast and evenings watching the sunset.
One night, Sarah asked me something unexpected.
“Do you miss your family?”
I thought about Thanksgiving dinners, birthday celebrations, and the little traditions I’d spent years trying to preserve.
“Sometimes,” I admitted.
“Would you go back?”
I watched the waves roll toward the shore.
“I’d consider rebuilding relationships if they took responsibility.
But I won’t go back to being their emergency bank account.”
Sarah smiled.
“That sounds like a different kind of freedom.”
She was right.
That November, almost one year after my mother slammed the door in my face, Dad sent me a Thanksgiving card.
Inside, he’d written:
I’m sorry I taught you that love meant carrying everyone else’s burdens.
You deserved better from us.
I kept the card.
I didn’t pretend it erased what happened.
But I appreciated that he’d finally acknowledged the truth.
Mom still hadn’t apologized.
Jason hadn’t either.
And I had stopped waiting.
On Thanksgiving morning, I stood in my kitchen preparing dinner for people who genuinely wanted to be there.
My phone buzzed.
It was a message from Dad.
“Happy Thanksgiving, sweetheart.
I hope you’re happy.”
I smiled and typed:
“I am, Dad.
I really am.”
Then I put my phone down and returned to the table.
For the first time in years, Thanksgiving wasn’t about keeping everyone else comfortable.
It was about sharing a meal without fear, guilt, or hidden obligations.
My family had mistaken my generosity for permission.
They thought that because I had always helped them, I would always allow them to use me.
They were wrong.
And the most important thing I learned wasn’t how to protect my money.
It was how to protect my peace.
Because sometimes, the family that shuts you out is the very family that teaches you how to open the door to a better life.